
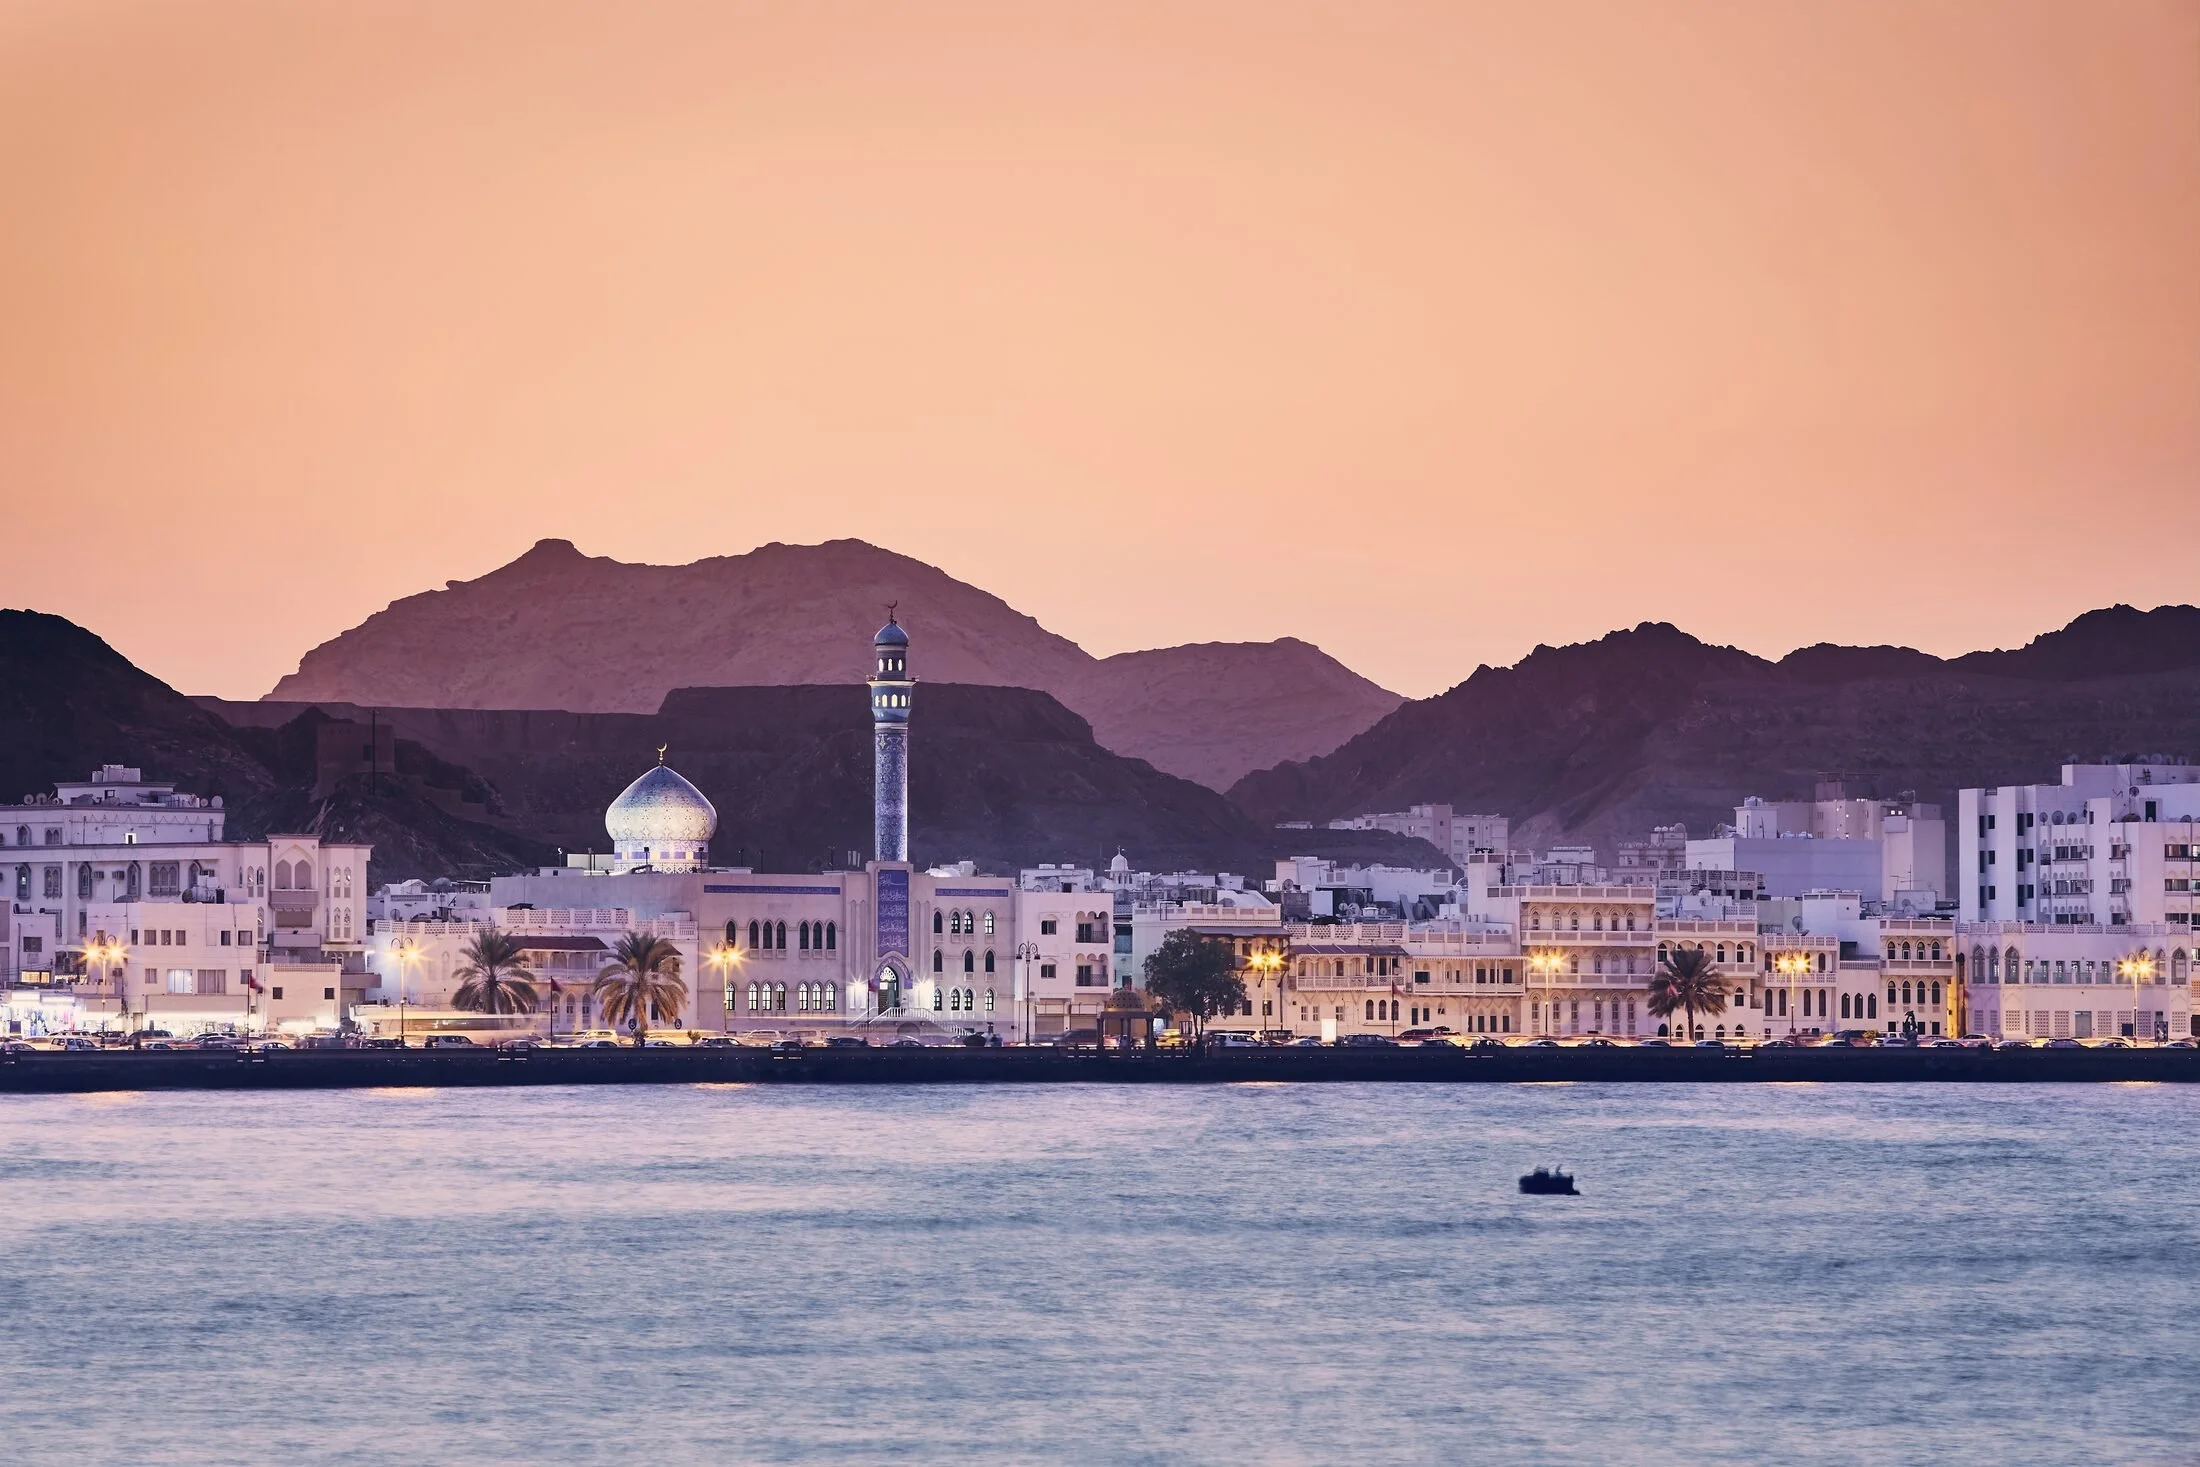
Oman Country Profile:
The Quiet Gulf Destination That Is Introducing the Gulf's First Personal Income Tax
Oman offers investor residency, freehold property in resort developments and a calmer, more traditional Gulf than the UAE, at lower cost. It is also the first GCC state to enact a personal income tax: zero until the end of 2027, then 5% on income above OMR 42,000 on a worldwide basis for residents. Plan on the 2028 rules, not the 2026 ones.
🇴🇲 Key Facts (2026):
Currency: Omani Rial (OMR); pegged at 0.3845 to USD (1 OMR ≈ USD 2.60)
Personal income tax: 0% until 31 December 2027; from 1 January 2028 a flat 5% on annual income above OMR 42,000 (~USD 109,000) after eligible deductions, on worldwide income for tax residents and on Oman-source income for non-resident Omani citizens
Corporate tax: 15% standard; 3% for qualifying Omani-owned small enterprises; 55% on petroleum extraction
Withholding tax: 10% on royalties, management fees and service fees paid to non-residents; withholding on dividends and interest suspended
VAT: 5% since April 2021; excise tax 100% on tobacco, energy drinks, alcohol and pork, 50% on sugary drinks
Capital gains: 0% for individuals; corporate gains taxed as income, with Muscat Stock Exchange listed securities exempt
Wealth tax: none
Estate/inheritance tax: none; Sharia succession rules apply to Muslims
Tax residency trigger: 183 days in a tax year under the Income Tax Law, the test that will also govern the 2028 personal tax
Investor Residency Programme: OMR 250,000 (~USD 650,000) for five-year residence; OMR 500,000 (~USD 1.3 million) for ten-year residence; property, company shares or government bonds qualify
Standard residency: employer-sponsored
Property purchase for foreigners: freehold in Integrated Tourism Complexes such as Al Mouj Muscat, Muscat Bay, Muscat Hills, Jebel Sifah and Hawana Salalah, with a residence visa attached to ownership
Corporate setup: OMR 2,000–5,000 (~USD 5,200–13,000) for a 100% foreign-owned LLC through Invest Easy. Annual maintenance: OMR 2,000–5,000 (~USD 5,200–13,000)
Personal bank account minimum: none with a resident card and salary letter; fee waivers from ~OMR 500 balance
Private banking threshold: roughly OMR 200,000–400,000 (~USD 520,000–1 million) at Bank Muscat, Sohar International and NBO
Cost of living, comfortable professional household: OMR 2,500–3,500 monthly (~USD 6,500–9,100)
CRS: participating; first exchanges 2020
FATCA: no intergovernmental agreement; Omani institutions comply directly with the IRS as participating foreign financial institutions
Treaties: roughly 35 comprehensive double tax agreements; none with Panama
Population: ~5.2 million, roughly 40% foreign nationals
Time zone: UTC+4, no daylight saving
Last edited: 22 September 2026 by Joe Martin Hanson (Director & Global Partner) with advice from FTR’s Omani Tax Partners
Why Oman Matters
Oman is emerging as a Gulf destination alongside the more established UAE, and it is emerging for a particular kind of client: one who wants Gulf regional access, security and low cost without Dubai's density, pace or price. Muscat is a low-rise coastal city between mountains and sea, the culture is more traditional and more courteous than anywhere else in the Gulf, and the state has spent a decade opening to foreign residents through 100% foreign company ownership, freehold resort property and the Investor Residency Programme introduced in 2021.
It matters also as a warning about the Gulf's tax trajectory. Oman is the first GCC state to enact a personal income tax, and although the rate is low and the threshold high, the principle that a Gulf resident is taxed on worldwide income has now been legislated in the region. A client moving to Oman in 2026 is moving to a country whose tax character changes on 1 January 2028, and the planning has to be done for the later regime.
Oman is a modest source of outbound wealth: Omani merchant families and senior professionals hold assets in the UAE, London and India, and the diaspora links with East Africa and South Asia are old. It is not a large HNW market and FTR should not treat it as one.
Visa and Residency Routes
Employer-sponsored residence is the standard route: the employer obtains the labour clearance and residence card, processing takes four to eight weeks, permits run two years, and Omanisation quotas make some roles unavailable to foreigners. It ends with the job.
Investor Residency Programme is the route FTR would use for a self-funded client. Introduced in 2021 and run by the Ministry of Commerce, Industry and Investment Promotion, it offers a ten-year renewable residence for an investment of OMR 500,000 or more, or a five-year residence for OMR 250,000 or more, with qualifying investments including a registered Omani company, property in an approved development and government bonds; a retired former resident with a monthly income of around OMR 4,000 has a separate five-year door. The card covers spouse and children, requires no employer, permits business ownership and takes a few weeks once the investment is documented. It leads to neither permanent residency nor citizenship, and it lapses if the investment is sold.
Property-linked residence attaches to freehold ownership in an Integrated Tourism Complex. A completed unit in Al Mouj Muscat, Muscat Bay, Muscat Hills, Jebel Sifah or Hawana Salalah entitles the owner and family to a residence visa for as long as it is held, at whatever the unit costs; a two-bedroom apartment at Al Mouj runs OMR 150,000–250,000, cheaper than the Investor Residency's lower tier, and this is the route most foreign retirees actually use. Since 2023 some non-resort areas have opened to foreigners on long usufruct.
Company ownership under the Foreign Capital Investment Law of 2019 allows 100% foreign ownership in most sectors with no minimum capital, and the company can sponsor its owner; it is a route for an operating business, not a residency device, because Omanisation and substance obligations are real.
Citizenship requires 20 years' residence, Arabic and discretion, is rarely granted, and dual nationality is not recognised. Not a plan.
Tax Peculiarities and Traps
The 2028 personal income tax. The Personal Income Tax Law enacted by Royal Decree in 2025 takes effect on 1 January 2028. A flat 5% applies to annual income above OMR 42,000 after deductions for education, healthcare, housing, zakat and charitable donations. Tax residents, Omani and expatriate alike, are taxed on worldwide income; non-resident Omani citizens are taxed only on Oman-source income. Employment income, business income, rent, dividends, interest and capital gains all count. For a professional on a typical expatriate package the threshold means little or no tax; for a business owner drawing OMR 200,000 a year it means OMR 7,900. The larger consequence is structural: from 2028 an Oman-resident client's Panamanian dividends are within the tax base, and the years in which Oman was a place to receive foreign income untaxed will have ended.
Tax residency at 183 days. The Income Tax Law already defines an individual resident as one present for 183 days or more in a tax year, and the 2028 tax will use it. Below 183 days a client is outside the personal tax but also without an Omani tax residency certificate, which matters for the home country.
Withholding tax and its suspension. A 10% withholding applies to royalties, management fees and service fees paid by Omani entities to non-residents. Withholding on dividends and interest has been suspended since 2019 and the suspension repeatedly extended, so an offshore holding company currently receives Omani dividends gross, on a basis that could be withdrawn.
The 3% small enterprise rate does not apply to foreigners. It is confined to Omani-owned small enterprises meeting capital, revenue and employee tests; a foreign-owned LLC pays 15% from the first rial of profit.
VAT at 5% with a real administration. Registration is mandatory above OMR 38,500 of annual supplies and voluntary above OMR 19,250, and non-resident suppliers of digital services to Omani consumers are within scope.
Sharia succession. A Muslim resident's Omani assets pass under Sharia shares through the courts; a non-Muslim's heirs may seek the law of nationality, bank accounts freeze on death, and Oman has no non-Muslim wills registry equivalent to the DIFC's.
The Structural Layer
For 2026 and 2027, FTR's default of a Panamanian Private Interest Foundation owning a Panamanian SA works in Oman as it does across the Gulf: no personal tax, no controlled foreign company rules, no exit tax, no tax on foreign-source personal income, and a residence provided by the employer, the property or the Investor Residency card rather than by the structure. The director's salary element is redundant while there is nothing to tax.
From 2028 the default needs adapting, and the adaptation should be built now. Oman will tax residents on worldwide income at 5% above OMR 42,000, and no CFC rule has been announced, so the SA's retained profits are outside the base until distributed and the foundation's undistributed assets are outside it altogether; only what the client actually draws is taxed. That makes the "modest director's salary paid where the person lives" relevant for the first time in a Gulf profile: a salary and dividends kept under or near the threshold, with the balance retained in the structure, is the natural shape. Two cautions. Oman has not yet published guidance on foreign entities and trusts and could yet introduce attribution rules before 2028; and the deductions regime is untested. Counsel should model the client's position under the 2028 law before recommending Oman as a base.
Omani operating activity belongs in an Omani LLC, 100% foreign-owned, taxed at 15%, with dividends flowing up gross under the current withholding suspension. Free zones at Sohar, Salalah, Duqm and Al Mazunah offer long tax holidays for businesses with a physical footprint and export orientation, subject to any Pillar Two top-up Oman adopts for large groups. For Omani families, the DIFC and ADGM foundations are the regional answer and Panama is the non-Gulf second leg.
Info-Sharing Reality (CRS and FATCA)
Oman joined the Common Reporting Standard later than its neighbours, with first exchanges in 2020, and now reports fully. Omani banks collect self-certifications and report non-resident-for-tax account holders to the Oman Tax Authority for onward transmission to India, Pakistan, Bangladesh, the Philippines, Egypt, the United Kingdom, the EU states and the other partners. Oman has no FATCA intergovernmental agreement; Omani banks report US persons directly to the IRS under their own participating-FFI registrations, which in practice means the same outcome with less local paperwork.
The 2028 tax changes the inbound direction. Today, a foreign bank reporting an Oman-resident client to the Oman Tax Authority produces nothing; from 2028 the Authority will have a use for that data, and a resident's undeclared foreign accounts become a domestic compliance problem for the first time in the Gulf. Clients who arrived in Oman under the old assumptions should be told this plainly. Oman has never been a secrecy jurisdiction, has a small banking sector wholly dependent on correspondent access, and is not a place to hide anything. Chinese HNW presence in Oman is negligible; the Plan-B lens does not apply.
Banking Reality
Bank Muscat is the dominant bank; Sohar International (which absorbed HSBC's Omani business in 2023), National Bank of Oman, Bank Dhofar, Ahli Bank, Oman Arab Bank, and the Islamic banks Bank Nizwa and Alizz complete a small market. A resident account needs the resident card, an employer letter or Investor Residency document, and a visit in person, and is opened within a week. Non-residents cannot open accounts in practice. Accounts are linked to the residence card and are expected to close on its cancellation.
Private banking is thin: Bank Muscat, Sohar International and NBO offer priority and private tiers from roughly OMR 200,000–400,000, with limited discretionary management; most Omani HNW families bank privately in Dubai, London or Switzerland. Oman sits on no FATF grey or black list, banks have full correspondent and SWIFT access, and compliance is conservative, particularly around Iran, with which Oman maintains open commercial relations.
Cost of Doing Business
A 100% foreign-owned Omani LLC registered through the Invest Easy portal, with a lease, commercial registration, chamber membership and a Ministry of Labour file, costs OMR 2,000–5,000 (~USD 5,200–13,000) to establish and about the same each year to maintain including registered office, accounting, VAT and tax filings, before Omanisation obligations. Against the set: a Panamanian SA costs roughly USD 1,500–2,500 to establish and USD 1,000–1,800 a year; Singapore runs about three times the Panamanian setup, USD 4,500–7,500, with USD 4,000–8,000 annual compliance; a UAE free-zone company sits at USD 5,000–12,000 to establish and USD 4,000–10,000 a year. Oman is cheaper than the UAE on setup and comparable on running costs, but carries a 15% corporate tax from the first rial, so it is a place for an operating business with Omani customers, not for a holding vehicle.
Cost of Living
Monthly, for Muscat. Rents run 30%–50% below Dubai and below Doha.
Lean, single or couple: OMR 900–1,300 (~USD 2,300–3,400): one-bedroom in Al Khuwair, Ghubra or Qurum OMR 300–450, groceries OMR 200–300, a used car and cheap petrol, employer-funded or mandatory expatriate health cover.
Comfortable, family of four: OMR 2,500–3,500 (~USD 6,500–9,100): villa in Madinat Sultan Qaboos, Qurum or Al Mouj OMR 900–1,500, two international school places at OMR 4,000–8,000 each per year, two cars, domestic help, private family health insurance OMR 1,000–2,500 a year.
HNW: OMR 6,000 and up (~USD 15,600+): a large Al Mouj or Muscat Bay villa, top-tier schooling, staff and travel.
Cultural and Practical Considerations
Oman is the gentlest of the Gulf states. Omanis are courteous and unhurried, the Ibadi tradition is tolerant, crime is very low, and Muscat has none of the ostentation of Dubai or the airlessness of Kuwait. For someone who wants quiet, sea and mountains and a society that still looks like itself, Oman is the best fit in the region; for someone who wants nightlife, speed and a large international scene, it will feel like a small town, because it is one.
Women. Expatriate women live, work, drive, rent and travel alone without legal constraint and with very little harassment; dress expectation is modest and observed rather than enforced. Family law applies Sharia to Muslims, with the custody and exit exposure for a foreign woman married to an Omani or Muslim husband common to the Gulf.
LGBT residents. Same-sex sexual activity is criminalised under the Penal Code with penalties of up to three years, there is no recognition or protection, and a same-sex spouse cannot be sponsored. Enforcement against discreet foreigners is rare; the risk is not zero.
Language and integration. English runs business and banking and is widely spoken in Muscat; Arabic controls contracts and courts and English thins quickly outside the capital. Integration with Omanis is more genuine than elsewhere in the Gulf because society is less segregated, and the expatriate community is smaller, older and less transient than Dubai's.
Alcohol, religion and conduct. Alcohol is served in licensed hotels and restaurants and available to non-Muslim residents by permit, made expensive by the 100% excise; public drunkenness is prosecuted, Ramadan restricts daytime eating in public, and criticism of the Sultan is a criminal matter.
Pace, bureaucracy and climate. Government works, slowly; Invest Easy and the residency portals have helped, but Omanisation and labour clearances are unpredictable. Muscat's summer runs above 45°C with coastal humidity from May to September, while Salalah's khareef makes the south green and mild in July and August. Distances are large and a car is essential.
Schooling. The British School Muscat, the American British Academy and the American International School are strong and rarely oversubscribed.
Politics and security. Sultan Haitham has governed since 2020 with cautious reform and a firm hand on public finances, of which the 2028 tax is part. Oman stayed out of the Qatar blockade, mediates between the United States and Iran and hosted the 2025 talks, and is the most insulated Gulf state from regional confrontation. Domestic incidents are rare but not unknown: youth employment protests in 2021 and a July 2024 attack on a Muscat mosque claimed by Islamic State.
For Retirees
The property-linked residence in an Integrated Tourism Complex above is the practical route and the most affordable Gulf retirement base; from 2028 pension income above OMR 42,000 is taxable at 5%, and home-country pension treatment should be checked against Oman's thin treaty network.
For Digital Nomads and Remote Professionals
No nomad visa; the Investor Residency or a property purchase is the way in, and the 2028 tax applies to remote income for residents.
For Online Business Owners and Entrepreneurs
Live in Oman, hold the business in the SA, draw modestly from 2028, and keep Omani activity in an Omani LLC only if there are Omani customers.
For Multinational Business Owners
A base for logistics, energy services and Indian Ocean trade through Duqm, Sohar and Salalah, with 15% corporate tax and free-zone holidays for real footprints.
For High Net Worth (HNW) Families and Investors
A comfortable, safe and cheap base with no permanent status and no citizenship; Omani families structure through Dubai with Panama as the non-Gulf second leg.
Common Traps
Choosing Oman as a zero-tax base in 2026 without planning for 2028: the zero is temporary and the client will be resident when it ends. Assuming Oman will remain outside worldwide taxation because the rate is low; the principle has been legislated. Buying off-plan in a resort for the residence visa and waiting years for handover. Using an Omani LLC as a holding vehicle at 15%. Expecting Dubai's banking depth, nightlife, or international scene. Anyone who needs pace, anonymity, a same-sex partner recognised, or an outdoor life in July. Anyone who cannot live with a residence that lapses when the property or investment is sold.
Next Steps
If Oman fits your Gulf planning, and particularly if you are already resident and have not yet modelled the 2028 personal income tax against your structure, book a scoping call.
Important note: General information. Not personal tax, legal, or financial advice. Speak to a qualified adviser at FTR or elsewhere before acting.
Continue reading
Suggested next, chosen by our partners.


