
Cyprus Country Profile:
The 60-Day EU Tax Residence, Rewritten for 2026
Cyprus offers the shortest defensible route to EU tax residence and a non-dom regime that removes tax on foreign dividends and interest for seventeen years, now extendable to twenty-seven. The 2026 reform raised corporate tax to 15%, loosened the 60-day rule and narrowed some of the non-dom advantage; the package is still the best in the EU for a mobile business owner.
🇨🇾 Key Facts (2026):
Currency: Euro; roughly USD 1.16 to the euro at mid-September 2026
Personal income tax: 0% to €20,500, then 20%, 25%, 30% and 35% above €80,000, under the bands effective 1 January 2026
Special Defence Contribution (SDC): dividends 5% for domiciled residents (cut from 17% in 2026), 0% for non-doms; interest 17% for domiciled residents, 0% for non-doms; rental income 0% for everyone from 2026
Non-dom regime: 17 years' exemption from SDC from the year of becoming resident; from 2026 extendable by two five-year blocks at €250,000 each, to 27 years
General Healthcare System (GESY) contributions: 2.65% on employment, dividend and rental income for employees and investors, 4% for the self-employed, on income up to €180,000
Corporate tax: 15% from 1 January 2026 (was 12.5%)
IP box: 80% deduction on qualifying IP profits, giving about 3% effective under the new rate
VAT: 19% standard; 9% and 5% reduced
Capital gains tax: 20% on Cyprus immovable property and shares deriving value from it; 0% on everything else
Wealth tax: none
Estate/inheritance tax: none (abolished 2000)
Tax residency trigger: 183 days, or the 60-day rule
60-day rule (2026): at least 60 days in Cyprus; not more than 183 days in any other single state; a permanent home owned or rented in Cyprus; and employment, business or directorship of a Cyprus tax-resident company that continues through the year. The former requirement not to be tax resident anywhere else was removed by the 2026 reform
Permanent residence by investment (Regulation 6(2)): €300,000 plus VAT in new residential property or other qualifying assets, plus annual foreign income of €50,000 (higher with dependants); two to four months
Digital Nomad Visa: net income of at least €3,500 per month; one year plus two renewals; capped numbers
Corporate setup: €1,000 to 3,000 (USD 1,150 to 3,500); annual compliance €2,000 to 6,000 (USD 2,300 to 6,950)
Personal bank account minimum: nil formally; residence or Cyprus employment expected; €1,000 to 5,000 initial deposit typical
Private banking threshold: €500,000 to 1 million investable
Cost of living, comfortable professional household: €5,000 to 7,500 per month (USD 5,800 to 8,700) in Limassol; 30% to 40% less in Larnaca, Paphos or Nicosia
CRS: participating, early adopter; first exchanges 2017
FATCA: Model 1 IGA, signed December 2014
Treaties: about 70 comprehensive double tax treaties
Population: about 1.38 million for the island (2026 estimate); the government-controlled area is roughly a million
Time zone: UTC+2, UTC+3 in summer
Last edited: 4 September 2026 by Joe Martin Hanson (Director & Global Partner) with advice from FTR’s Cypriot Tax Partners
Why Cyprus Matters
Cyprus is the only EU member state where an individual can become tax resident on sixty days' physical presence a year, and since the 2026 reform that residence no longer collapses merely because another country also regards the person as resident. For a business owner or investor who genuinely moves between three or four countries and needs one defensible EU tax residence with a certificate behind it, nothing else in the EU competes.
The non-dom regime is the second reason. A resident who is not Cyprus-domiciled pays no Special Defence Contribution on dividends or interest from anywhere, for seventeen years, now extendable to twenty-seven. Combined with income tax exemptions on dividends, the 50% exemption on high employment income for new residents, no capital gains tax on securities and no inheritance tax, the effective personal rate for an investor or owner-manager is very low, legally and in full view of every tax authority that asks.
The third reason is corporate. At 15% Cyprus is no longer the cheapest headline rate in the EU, but the IP box at about 3%, the notional interest deduction, no withholding on outbound dividends, interest or royalties to most jurisdictions, a full treaty network and cheap incorporation still make it the practical holding and IP location for a client whose personal residence is also here, which is the combination FTR sells.
The reform itself matters: it was drafted to keep Cyprus inside the OECD and EU tent after the golden passport scandal and the Russian de-risking of 2018 to 2022, and it succeeded in making the jurisdiction more boring and more defensible at once.
Visa and Residency Routes
EU/EEA nationals register within three months for a registration certificate (the yellow slip) on the basis of employment, self-employment or self-sufficiency, and the tax rules take over from there.
Permanent Residence by Investment (Regulation 6(2)). Third-country nationals invest €300,000 plus VAT in new residential property from a developer, or the same amount in commercial property, shares of a Cyprus company employing at least five people, or Cyprus registered investment funds, and show secure annual income from abroad of at least €50,000, plus €15,000 for a spouse and €10,000 per child under the rules tightened in May 2023. Processing is two to four months. The permit is permanent, requires only one visit every two years, and covers spouse and dependent children. It confers no right to work as an employee, though the holder may be a director and shareholder. It is the route FTR uses for a non-EU HNW family that wants a secure EU foothold and the 60-day residence as an option.
Temporary residence for financially independent persons (the pink slip). For third-country nationals with foreign income of roughly €24,000 a year plus a dependant increment, a Cyprus lease and health insurance; renewable annually, no employment permitted. Cheap and slow to process; the choice for a retiree or a nomad's spouse who does not want to buy property.
Digital Nomad Visa. Third-country remote workers with net monthly income of at least €3,500 (plus 20% for a spouse and 15% per child), one year renewable twice, capped at 500 permits. It buys legal presence; the tax residence comes from days, not from the visa.
Employment through a foreign-interest company. A Cyprus company with majority foreign ownership, €200,000 of invested capital and real offices can register with the Business Facilitation Unit and employ third-country nationals at a minimum salary of €2,500 a month, with family reunification. This is how a non-EU business owner brings themselves and key staff in under a work permit, and it pairs naturally with the 60-day rule's employment condition.
Naturalisation. Ordinarily seven years' legal residence, with a Greek language requirement since the 2023 amendments; highly skilled employees of foreign-interest companies can apply after four years, or three with a higher Greek standard. Processing has been slow. The Cyprus Investment Programme that sold passports was abolished in November 2020 after the Al Jazeera revelations and will not return.
What looks good on paper but fails: the Digital Nomad Visa for a nomad whose home country still taxes them; the pink slip for anyone who wants to work; and the belief that the 60-day rule works for someone who is spending 250 days a year in one other country.
Tax Peculiarities and Traps
The 60-day rule after the reform. From 1 January 2026 the test is: at least 60 days in Cyprus; not more than 183 days in any other single state; a permanent home in Cyprus, owned or rented, throughout the year; and a Cyprus employment, business or directorship of a Cyprus tax-resident company that is not terminated during the year. The condition that the person not be tax resident in any other state has been removed. That is a real relaxation, but it does not mean dual residence is safe: if another country also treats the person as resident, the treaty tie-breaker decides, and a client with a permanent home, spouse and business in Germany will lose that tie-breaker regardless of the Cyprus certificate. The 60-day rule is for people who are genuinely nowhere else for more than 183 days.
Domicile and the 17-year clock. Non-dom status turns on domicile of origin under the Wills and Succession Law and on a look-back: a person who has been Cyprus tax resident for 17 of the previous 20 years is deemed domiciled and loses the exemption. The 17-year window runs from the first year of residence and can now be extended by paying €250,000 per five-year block for up to two blocks. Cypriots returning after long absence are the usual casualties: a Cyprus domicile of origin is not cured by twenty years in London unless the look-back test is also met.
The narrowed non-dom advantage. The 2026 reform cut SDC on dividends for domiciled residents from 17% to 5% and abolished SDC on rental income for everyone. Non-doms still pay zero on dividends and interest, but the gap on dividends is now 5 points rather than 17, and there is no longer any non-dom advantage on rent. Interest for domiciled residents remains at 17%. The non-dom regime is still valuable; it is no longer the difference between everything and nothing.
GESY on investment income. The General Healthcare System levy of 2.65% applies to dividends, interest and rent as well as salary, capped at €180,000 of income, and non-dom status does not exempt it. An owner-manager taking €500,000 in dividends pays about €4,770 of GESY and no SDC. It is small, and it surprises people.
Employment income exemptions. New residents taking up first employment in Cyprus with annual pay above €55,000 get 50% of it exempt for 17 years under Article 8(23A); those below it get 20% (up to €8,550) for seven years. Foreign pensions can be taxed at a flat 5% above €3,420. These are elections, and the wrong one costs money.
Capital gains on property. 20% on gains from Cyprus immovable property and on shares in companies holding it, with a lifetime allowance; nothing on securities, crypto or foreign property. Stamp duty and a transfer fee or VAT apply on purchase, and VAT at 5% on a first home is available only on the first 130 square metres under the 2023 rules.
Deemed dividend distribution. A Cyprus company that does not distribute at least 70% of its after-tax accounting profits within two years is deemed to have distributed them, and SDC and GESY are charged on the resident shareholders' share. Non-dom shareholders are outside SDC, so the deemed distribution costs them only GESY, but the rule catches domiciled shareholders and it catches the unwary who thought retained profits were untaxed.
Withholding on payments to listed jurisdictions. Since 2023 Cyprus withholds on dividends, interest and royalties paid to companies in EU-blacklisted jurisdictions, and the 2026 reform extends the approach to low-tax jurisdictions. Payments to Panama need checking against the current list before any structure assumes zero withholding.
The Structural Layer
FTR's default, a Panamanian Private Interest Foundation over a Panamanian SA with a modest director's salary paid where the client lives, needs adapting in Cyprus, and the adaptation is the point of coming here. Cyprus has no personal CFC rules, so the Panamanian SA is not attributed to the resident; but the 60-day rule requires a Cyprus employment, business or directorship of a Cyprus-resident company, and the banks want to see Cyprus substance. So the standard structure is a Cyprus operating or holding company, resident and managed in Cyprus, owned by the Panamanian foundation, with the client as its salaried director. The Cyprus company pays 15% (or about 3% on IP-box income), distributes dividends free of withholding to the foundation, and the client's own dividends and any foreign dividends are SDC-free under non-dom status. The director's salary is taxed at progressive rates with the 50% exemption where the €55,000 threshold is met.
Where the Panamanian SA still earns its place is as the non-EU operating company for business that genuinely happens outside the EU, sitting beside the Cyprus company rather than under it, with the foundation above both. Payments between the two need arm's-length pricing and a check against the Cyprus withholding list.
The foundation is the succession layer. Cyprus has no inheritance tax, so the driver is control and continuity, and Cyprus courts recognise foreign foundations and trusts readily; Cyprus International Trusts under the 1992 law, as amended in 2012, are an alternative for a client who prefers an EU-law trust with no Cyprus tax on foreign income of non-resident beneficiaries.
Where the default plainly does not fit: a client who remains resident in a home country with CFC rules (Germany, Italy, Spain, France, the UK, Australia, Canada, the US, China) and merely holds a Cyprus certificate; the Cyprus company and the Panamanian layer are attributed at home and the residence claim fails the tie-breaker. Corporate CFC rules under ATAD apply to Cyprus companies with low-taxed subsidiaries, and Cyprus applies the EU anti-hybrid rules, so a Cyprus company owning a Panamanian SA must be able to show the SA is not merely a passive low-tax pocket.
Info-Sharing Reality (CRS and FATCA)
Cyprus was an early adopter of the Common Reporting Standard, exchanging from 2017, and Cyprus banks, investment firms, fund administrators and trustees report non-resident account holders and controlling persons to the Tax Department for automatic exchange with all EU states under DAC2 and with the UK, Switzerland, Canada, Australia, Singapore, the UAE, Israel, Panama, Russia while exchanges were active, and China. A Chinese HNW family with a Cyprus company, a Limassol apartment held through it, and a Bank of Cyprus account is reported to Beijing on the controlling-person basis; the Cyprus route has been used by Chinese families for EU access and it delivers no confidentiality from the Chinese authorities. Under the FATCA Model 1 IGA signed in December 2014, US persons' accounts are reported to the Tax Department for the IRS.
Cyprus has spent a decade being reported on rather than reporting. The 2013 bail-in, the 2018 shell-company circular that closed thousands of accounts, the 2020 golden passport scandal, and the 2023 US and UK sanctions against Cypriot lawyers and corporate service providers for Russian sanctions evasion have all left a mark. The result is a jurisdiction whose banks and regulators over-comply: source-of-wealth checks are thorough, Russian and Belarusian clients are largely gone, and the beneficial ownership register is live. Anyone still marketing Cyprus as a discreet offshore centre is describing 2012.
The 60-day certificate is issued by the Tax Department and is exchanged and challenged like any other. Home countries that see a Cyprus residence certificate from a person with a home and family elsewhere ask for the day count, the lease and the employment contract. Have them.
Banking Reality
Bank of Cyprus, Eurobank Cyprus (which absorbed Hellenic Bank after Eurobank's 2024 acquisition), Alpha Bank Cyprus, AstroBank, Ancoria Bank and cdbbank. All are ECB-supervised or ECB-overseen, have full SWIFT access and functioning USD correspondent relationships; the 2018 to 2022 de-risking removed the shell-company clientele that had strained those relationships. Cyprus is on no FATF or EU list as at 2026.
Personal accounts for residents open in two to six weeks with a residence permit or yellow slip, a Cyprus address, proof of income and, for non-EU nationals, an employment contract or the permanent residence approval; an in-person visit is expected. Non-resident accounts are possible for clients with a Cyprus property purchase or company in progress, at the bank's discretion, and take longer. Initial deposits of €1,000 to 5,000 are typical; there is no formal minimum. Nationals of Russia, Belarus and sanctioned jurisdictions face refusal or closure; nationals of high-risk third countries face enhanced due diligence that can run to months. Private banking at Bank of Cyprus Wealth and Eurobank Private starts around €500,000 to 1 million investable.
Corporate accounts for Cyprus companies with a licensed administrator, real activity and a Cyprus-resident director open in four to ten weeks. Companies whose only activity is holding a Panamanian or BVI subsidiary are questioned; companies in gaming, crypto or forex are sent to the EMIs. Payment institutions and Revolut Business cover the gap for small operators.
Cost of Doing Business
A Cyprus private limited company costs €1,000 to 3,000 to incorporate (USD 1,150 to 3,500) through a lawyer or licensed administrator, with registry fees, registered office and no minimum capital in practice. Annual compliance is €2,000 to 6,000 (USD 2,300 to 6,950) for the statutory audit (mandatory for all companies), tax return, annual return and registered office; the €350 annual levy was abolished in 2024. A Cyprus-resident director, a lease and a local employee for substance add €10,000 to 30,000 a year and are increasingly expected by banks and by home-country authorities.
Against the set: a Panamanian SA is USD 1,500 to 2,500 to establish and USD 1,000 to 1,800 a year; Singapore about three times Panama, USD 4,500 to 7,500 setup and USD 4,000 to 8,000 a year; Malta €1,500 to 4,000 setup and €3,000 to 8,000 a year, so Cyprus is slightly cheaper than Malta at every stage and its 15% rate is simpler than Malta's refund mechanism but higher than Malta's 5%. Ireland is cheaper to incorporate, at 12.5% for trading income, and harder to live in cheaply.
Cost of Living
Limassol is where business clients go and it has become expensive; Nicosia, Larnaca and Paphos are 30% to 40% cheaper on housing and are where retirees and families on a budget settle. Monthly figures for Limassol.
Lean, single or couple: €2,500 to 3,500 (USD 2,900 to 4,050): one-bedroom €1,200 to 1,800, groceries €400 to 600, GESY through contributions with private top-up €60 to 120, a small car €300 to 450 all-in; buses are inadequate and a car is not optional.
Comfortable, family of four: €5,000 to 7,500 (USD 5,800 to 8,700): three-bedroom apartment or house €2,500 to 4,500, private health insurance €200 to 350, two cars €700 to 1,000, two places at an English-language private school (Heritage, American Academy, Foley's, Pascal, The Grammar School) at €8,000 to 15,000 each per year, groceries and utilities €1,000 to 1,500.
HNW: €12,000 to 25,000 (USD 13,900 to 29,000): a seafront tower apartment or villa in Agios Tychonas or Mouttagiaka at €6,000 to 12,000, domestic help, two good cars, boat berth at Limassol Marina and travel.
GESY, the national health system launched in 2019, is decent for primary and emergency care and slow for elective work; most clients carry private cover. State schools teach in Greek; expatriate children go private.
Cultural and Practical Considerations
Cyprus is a Greek-speaking, Orthodox, family-centred Mediterranean society with an English-language business layer inherited from British rule and reinforced by thirty years of international clients. The fit questions are about heat, driving, the pace of administration and the division of the island.
Women, LGBT residents and family law. No legal or practical constraint on women travelling, residing, holding property or doing business alone; Limassol's business community has many women in senior roles, and village society is conservative but not restrictive. Civil partnerships for same-sex couples have existed since 2015; there is no same-sex marriage, adoption rights are limited, and the Church is loud on the subject, but there is no enforcement risk and Limassol and Nicosia are relaxed in practice. Family law is civil and equal on paper; divorce and custody proceedings are slow and the Church's influence on family matters is cultural rather than legal.
Language and integration. English is enough for banks, lawyers, doctors, the Tax Department and daily life in the coastal cities; Greek is needed for the village, for the civil service at lower levels and for naturalisation. Cypriot society is warm on the surface and closed underneath, organised around extended family and the village of origin; foreigners are welcomed as customers and neighbours and rarely as family. The foreign community, with strong British, Russian-speaking, Israeli, Lebanese and Ukrainian components, is large enough in Limassol to be a complete social world and substitutes for integration for most people.
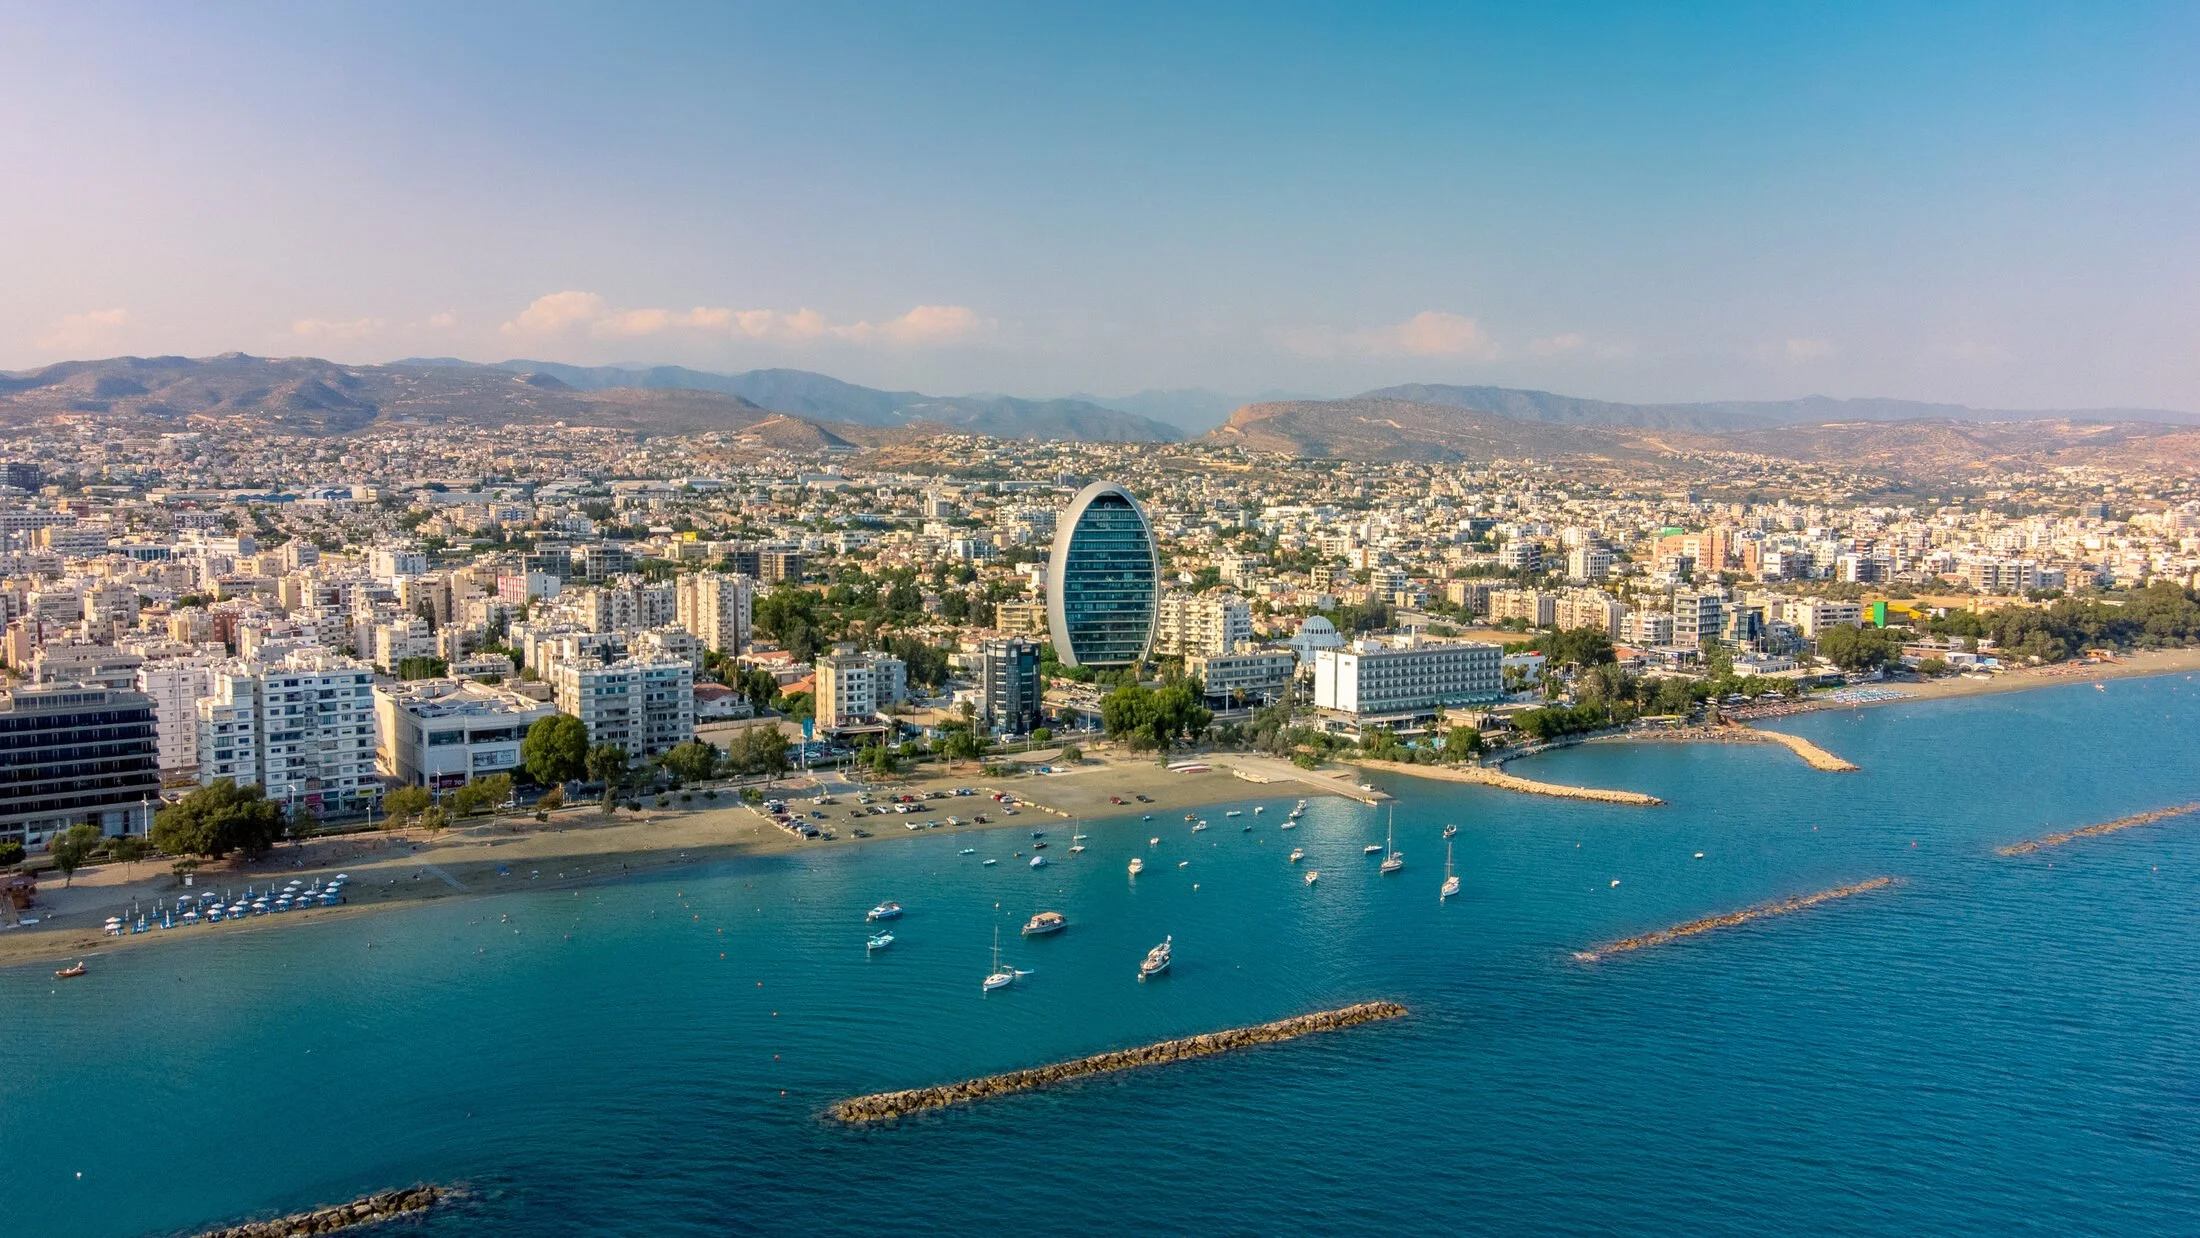
Pace, noise, chaos and security. Limassol is a construction site with a seafront: towers going up, traffic that has outgrown the roads, and a high-rise skyline that a decade ago did not exist. Someone who came for a quiet Mediterranean island should go to Paphos or the Troodos foothills instead. Administration runs on Cyprus time. Personal security is excellent; violent crime is among the lowest in the EU.
Bureaucracy and time. The Civil Registry and Migration Department, the Land Registry and the District Offices are slow, paper-driven and appointment-based. Things get done, generally through a lawyer who does them for a living. Title deeds on new developments can lag years behind completion, which is a live risk in a property-linked residence application.
Climate and health. Summers run to 40 degrees from June to September with dust episodes from the Middle East; winters are mild and short. Heat-intolerant clients and those with cardiovascular or respiratory conditions notice the summers, and air conditioning is a large line in the electricity bill.
The division of the island. The north has been under Turkish occupation since 1974 and property there is a legal trap: title to most of it is contested by displaced Greek Cypriot owners, EU judgments are enforceable against buyers, and no reputable adviser will touch it. The Green Line is porous for day trips and irrelevant to daily life in the south, but the frozen conflict is a permanent political fact and the occasional flare-up in rhetoric is felt.
Schooling and politics. English-language private schools are good and oversubscribed in Limassol; apply early. Politics is a stable presidential democracy with a strong Communist party, a pro-European centre-right presidency, and public cynicism about the corruption revealed by the passport scandal. A resident feels none of it beyond the news.
For Retirees
The pink slip or permanent residence above, the 5% flat rate on foreign pensions, no inheritance tax, and Paphos or Larnaca rather than Limassol; UK retirees have been doing this for fifty years and the infrastructure for them exists.
For Digital Nomads and Remote Professionals
The 60-day rule above, with a Cyprus company directorship and a rented flat, is the most defensible EU residence available to someone genuinely on the move; the Digital Nomad Visa handles presence for non-EU nationals but does not by itself make anyone tax resident.
For Online Business Owners and Entrepreneurs
The Cyprus company under the Panamanian foundation as described in the Structural Layer: 15% or the IP box, SDC-free dividends, 50% salary exemption, 60 days on the island.
For Multinational Business Owners
A Cyprus holding or IP company for EU operations at 15% and about 3%, with substance, the notional interest deduction and the treaty network; the 2026 rate rise removed the cheapest headline in the EU but not the practical case.
For High Net Worth (HNW) Families and Investors
Permanent residence at €300,000 with no stay requirement, the non-dom regime for the day they move, and eventual naturalisation after seven years and Greek lessons. For Chinese HNW families Cyprus has been a popular EU foothold and remains one; the reporting to China is complete and the passport is no longer for sale.
Common Traps
Claiming 60-day residence while living 250 days a year somewhere else. The removal of the "not resident elsewhere" condition does not neutralise the other country's claim or the treaty tie-breaker, and the home country will ask for the lease, the contract and the day count.
Returning Cypriots expecting non-dom status. A Cyprus domicile of origin and the 17-of-20-years look-back mean many do not qualify.
Buying property in the north.
Coming to Limassol for a quiet, cheap Mediterranean life: it is loud, built-up and priced like a northern European city.
Expecting the corporate rate to be 12.5%; it is 15% from 2026, and a structure priced on the old rate needs re-running.
Anyone with a Russian or Belarusian passport, or a business in gaming, crypto or forex, should assume the domestic banks will not have them and plan around EMIs.
Next Steps
If a 60-day EU residence with a non-dom regime and a Cyprus company underneath fits your facts, book a scoping call; the day-count model, the home-country tie-breaker and the substance plan are what we settle first.
Important note: General information. Not personal tax, legal, or financial advice. Speak to a qualified adviser at FTR or elsewhere before acting.
Continue reading
Suggested next, chosen by our partners.


