
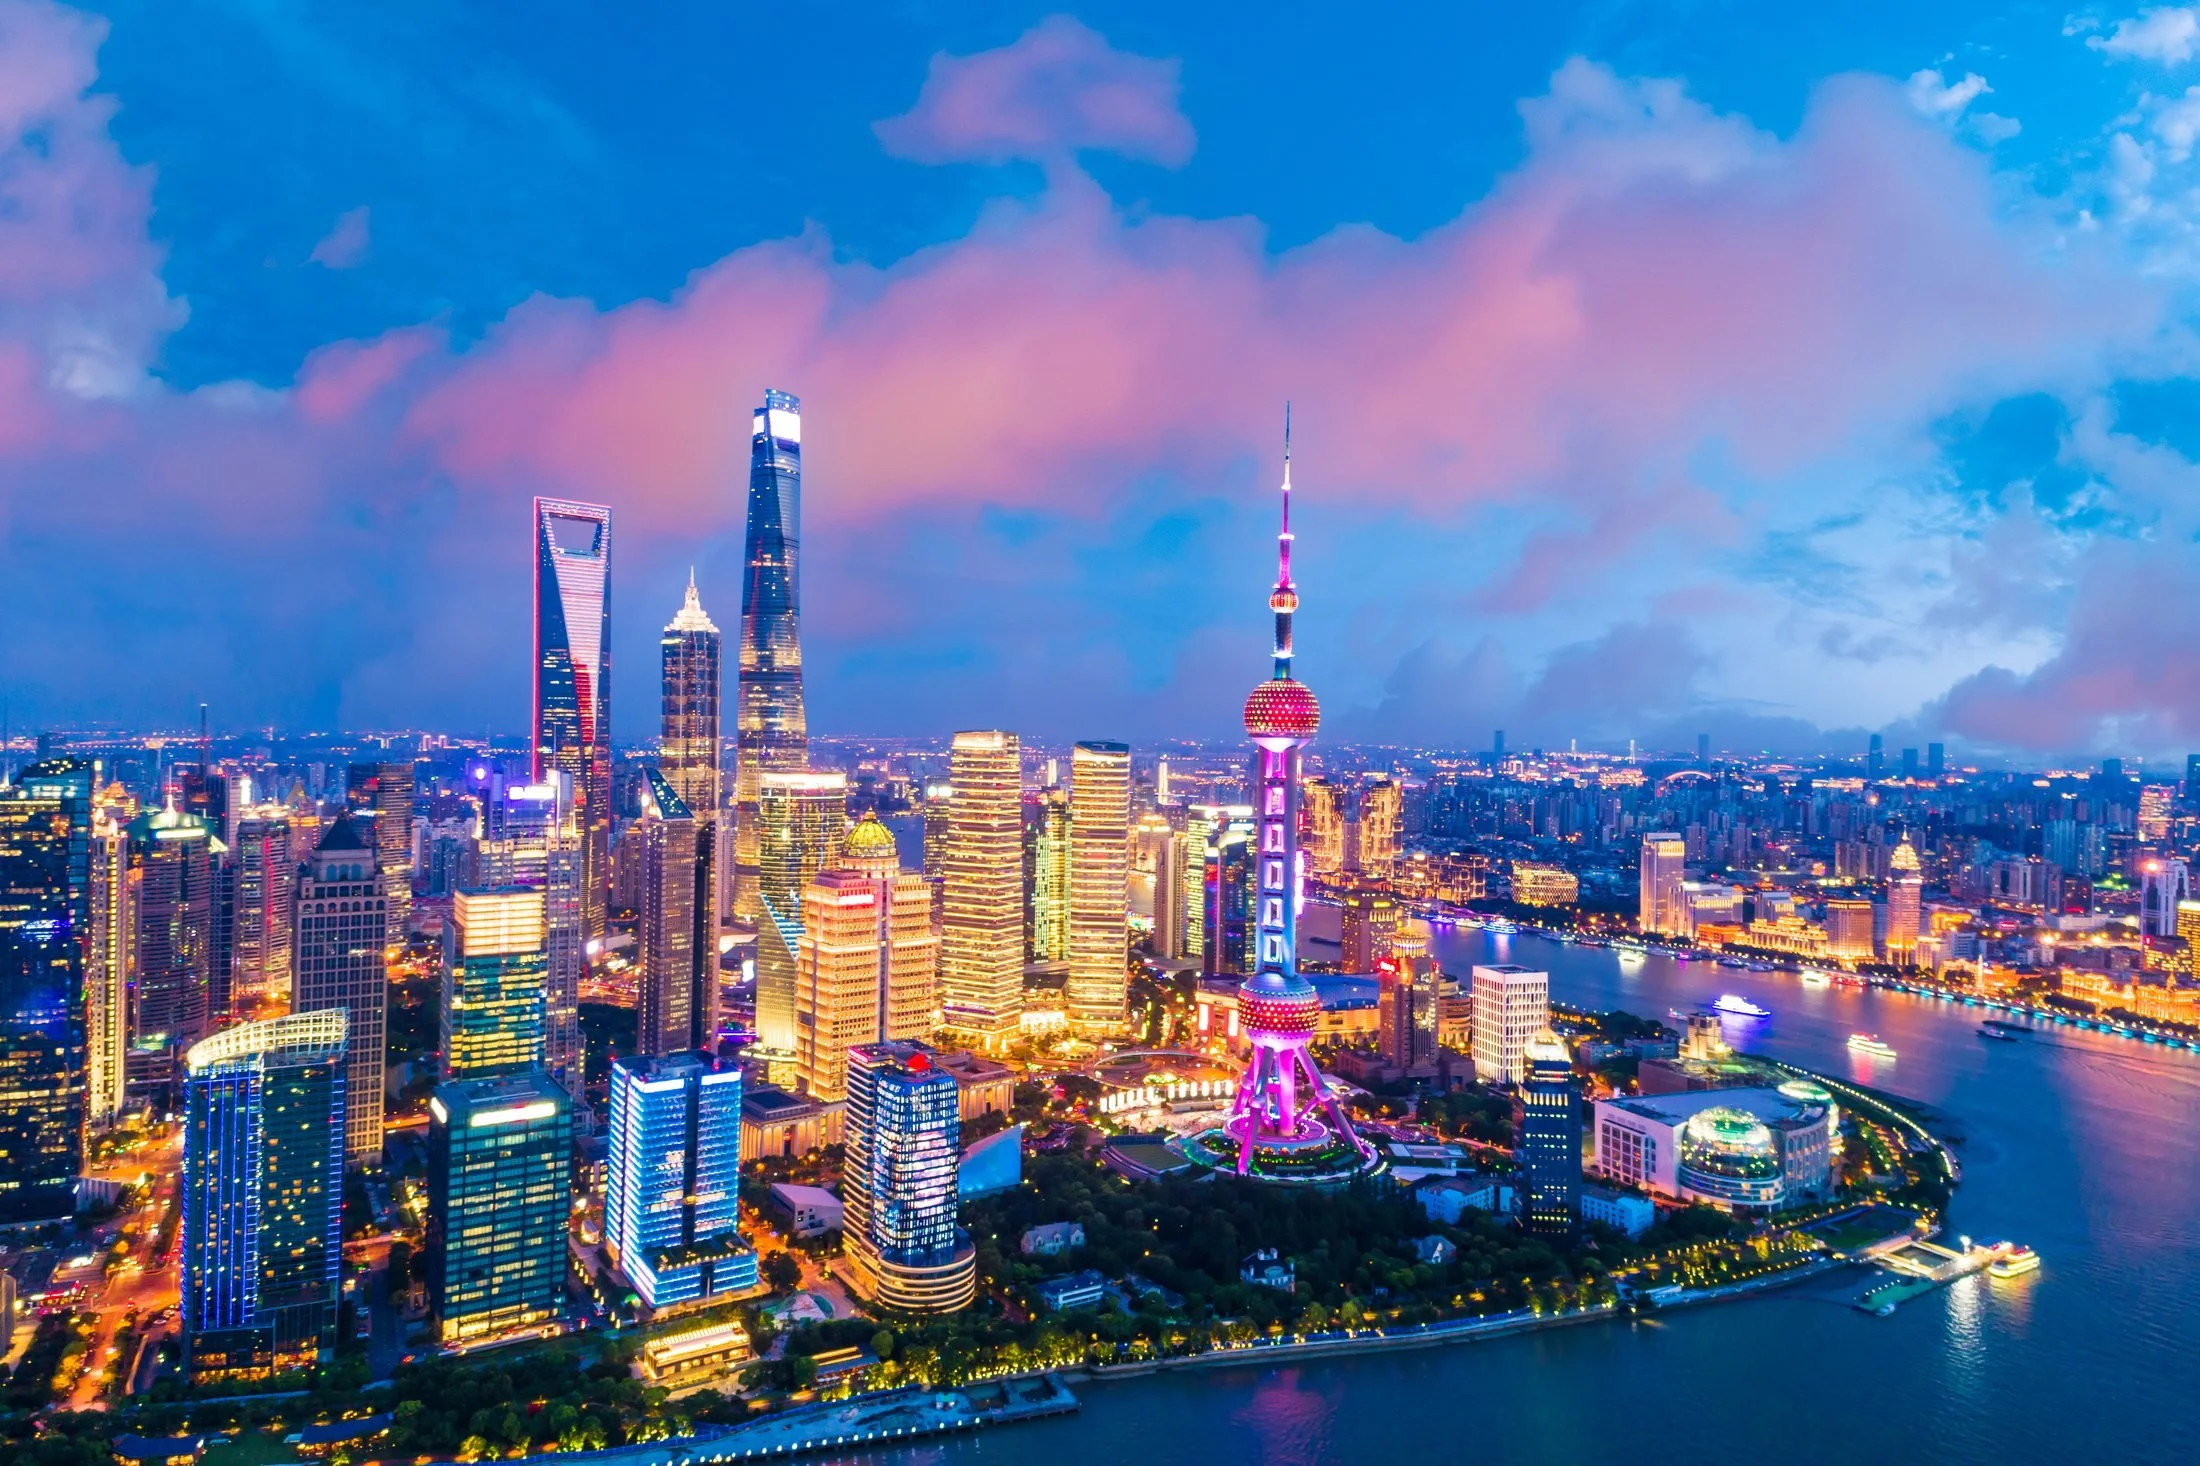
China Country Profile:
The World's Largest Wealth-Exit Story, and What Can Lawfully Leave
China is a source country, not a destination. The work is moving a family's tax residency, its members and its lawfully exported capital somewhere durable, in a world where CRS makes most of the destinations Chinese families prefer transparent to Beijing.
🇨🇳 Key Facts (2026):
Currency: Chinese yuan renminbi (CNY); roughly 6.7 to the USD in mid-September 2026. Onshore CNY and offshore CNH trade at slightly different rates.
Personal income tax: 3% to 45% progressive, seven brackets on comprehensive income; the 45% bracket starts at CNY 960,000 of annual taxable income, about CNY 80,000 a month.
Corporate tax: 25% standard; 15% for High and New Technology Enterprises; reduced effective rates for small low-profit enterprises.
VAT: 13%, 9% and 6% by activity, with a 3% simplified rate for small-scale taxpayers; the new VAT Law took effect 1 January 2026 and kept the rates.
Capital gains: no separate regime; gains are income from transfer of property at a flat 20% for individuals. Gains by individuals on listed A-shares are exempt. Gains by mainland individuals on Hong Kong shares bought through Stock Connect sit under a temporary exemption that has been renewed repeatedly, currently to the end of 2027.
Dividends: 20% for individuals; A-share dividends are exempt when the shares have been held over a year and half-taxed between one month and a year.
Wealth tax: none.
Estate and inheritance tax: none; discussed for two decades, never legislated. No gift tax.
Property tax: pilot levies in Shanghai and Chongqing only; no national tax.
Exit tax: none for individuals.
Tax residency trigger: domicile, meaning habitual residence in China by reason of household registration (hukou), family or economic interests; or 183 days in a calendar year for the non-domiciled.
Six-year rule: non-domiciled residents are exempt on foreign-source income paid by foreign parties until they have been resident for 183 or more days in each of six consecutive years with no single absence of more than 30 days.
Individual foreign exchange quota: USD 50,000 per person per year, administered by SAFE; overseas ATM cash withdrawals capped at CNY 100,000 a year per person; cash above USD 5,000 must be declared at the border.
Foreign income reporting: declared in the annual reconciliation return filed 1 March to 30 June; there is no separate foreign asset register.
Nationality: dual nationality is not recognised; naturalising abroad ends Chinese nationality by operation of law.
Inbound visa thresholds: no investor or retiree residency route of consequence; work (Z) and talent (R) visas are the practical routes; permanent residence is rare.
Corporate setup (WFOE): USD 5,000 to 15,000 through an agent; annual maintenance USD 5,000 to 15,000.
Personal bank account minimum: none of substance for residents. Private banking: CNY 6 million to 10 million in financial assets at the large banks.
Cost of living, comfortable professional household: USD 3,000 to 5,000 a month in Shanghai or Shenzhen before international schooling.
CRS: participating; first exchanges September 2018.
FATCA: no signed intergovernmental agreement. An agreement in substance on Model 1 terms has existed since June 2014 and remains unsigned; Chinese financial institutions have not implemented IGA reporting.
Treaties: more than 100 double tax agreements, including the United States, United Kingdom, Australia, Canada, Singapore, Switzerland and the UAE, plus an arrangement with Hong Kong. None with Panama and none with Colombia.
Population: about 1.41 billion and now declining.
Time zone: UTC+8, a single zone nationwide.
Last edited: 16 September 2026 by Joe Martin Hanson (Director & Global Partner) with advice from FTR’s Chinese Tax Partners
Why China Matters
The movement of Chinese private wealth abroad is the largest cross-border wealth story of this century. Industry estimates of net millionaire outflows run to the low five figures a year, and the number of families who have relocated part of their wealth, their children or themselves over the past decade runs to the hundreds of thousands. A substantial portion of FTR's HNW work involves Chinese-connected families, and almost none of it involves anyone moving to China.
The motivations are consistent and legitimate: political risk to person and property, preservation of wealth across generations, education for children, currency diversification away from a managed currency behind capital controls, and the plain desire for an exit that does not depend on the goodwill of the state. The 2021 crackdowns on private tutoring, technology and property, and the zero-Covid years, converted a theoretical concern into a lived one for a generation of business owners.
What makes China different from every other source country in this series is the combination of three constraints. Capital controls limit what can lawfully leave. Domicile-based tax residency means leaving physically does not end Chinese taxation. And CRS means the destinations Chinese families instinctively prefer, Singapore, Hong Kong, Switzerland, the UAE and the Cayman Islands, all report back to the State Taxation Administration for as long as the client remains a Chinese tax resident. The planning has to solve all three, in the right order.
Panama's role is narrower than for most FTR clients: not a destination, but a USD-denominated structural layer for families with Americas exposure or a wish to spread holdings across jurisdictions that do not share a regulator.
Visa and Residency Routes
China is not a residency destination for FTR's readers, and its inbound routes are covered only so that a client posted there understands them. The Z work visa, converted to a residence permit after arrival, is the standard route and is tied to a licensed employer. The R visa for high-level talent is faster and less bureaucratic but discretionary. Family reunion permits follow a Chinese spouse or parent. Permanent residence exists on paper and is granted to a few thousand people a year, mostly senior executives, investors and spouses of long standing; nobody should plan around it. Visa-free entry for short stays has been widened considerably since 2024, which helps business visitors and does nothing for residency. None of these routes carries a path to citizenship worth describing, since naturalisation is almost never granted.
The residency question for this profile is the one Chinese clients ask: where to go. Singapore is the first choice for banking and family office structures, and it is now the most demanding on source of funds. The United States, Canada and Australia are chosen for education and family life, historically through EB-5, provincial and state investor programmes, and student-to-family sequencing; the United States has the added attraction, covered below, of sitting outside CRS. The United Kingdom has lost ground since the non-dom regime closed. Portugal drew Chinese families for a decade until the property route of its Golden Visa shut. Hong Kong remains the natural first step, functional and familiar, but no longer read as a political exit. The UAE has grown fastest, for zero personal tax, geographic distance and an accommodating visa system. Switzerland is chosen for quality of institutions rather than privacy. Panama serves a smaller group wanting USD structures and Americas-facing holdings.
The route that fails in practice is the one that treats a foreign residence card as the finish line. A Chinese national who holds a Singapore permanent residence, a Golden Visa or a Canadian card while keeping hukou, home, spouse and business in China has changed nothing about Chinese tax residency and nothing about what CRS delivers to Beijing. FTR's advice to every Chinese-connected client begins with the tax residency exit, not the visa.
Tax Peculiarities and Traps
Domicile is the test, not days. The Individual Income Tax Law taxes anyone domiciled in China on worldwide income, and domicile is habitual residence by reason of household registration, family or economic interests. A Chinese national with an active hukou, a spouse and a company in China is domiciled whatever the day count says. Foreign permanent residence does not displace it. Breaking domicile requires the habitual home, the family and the economic centre to move, evidenced over time, and the State Taxation Administration has no formal exit certificate to confirm it. The cost of misjudging this is Chinese tax on worldwide income, with CRS data now used to find it.
The six-year rule works for foreigners, not for returning Chinese. Under the 2019 rules, a non-domiciled individual resident 183 or more days a year pays Chinese tax only on China-source income and on foreign income paid or borne by Chinese entities, until six consecutive qualifying years have accumulated. A single absence of more than 30 consecutive days in any year resets the clock, and the count began in 2019. Executives on rotation use the 30-day break deliberately. A Chinese national cannot use the rule at all unless domicile has genuinely been lost, which is the previous trap.
Annual reconciliation and the 2025 overseas income campaign. Comprehensive income and foreign-source income are declared in the annual reconciliation between 1 March and 30 June. For years this was widely ignored for offshore income. In 2025 tax bureaus in several provinces publicly announced recoveries from individuals with undeclared overseas investment income, matched from CRS data, with penalties and late-payment interest. The assumption that Beijing receives the data but does not act on it is no longer safe.
SAFE Circular 37. A Chinese resident who sets up or acquires an offshore special purpose vehicle, the classic BVI or Cayman company above an operating business or investment portfolio, must register it with SAFE. Unregistered structures cannot lawfully repatriate profits, cannot be used to inject onshore assets, and expose the individual to penalties. Most historic Chinese offshore holding structures were built around this rule; many were never registered.
The quota and the watchlist. The USD 50,000 annual purchase quota covers travel, education and modest living costs and nothing else. Larger remittances for property, investment or emigration require purpose-specific approval that is rarely granted. Splitting a transfer across relatives' quotas, known as ant moving, is prohibited and puts every participant on SAFE's watchlist, typically for three years, during which even the standard quota is withdrawn. Underground banking and matched swaps of onshore and offshore funds are criminal. Cryptocurrency trading has been banned for residents since 2021.
The individual anti-avoidance rule. Article 8 of the Individual Income Tax Law, added in 2019, lets the tax authority attribute to a Chinese-resident individual the undistributed profits of a company they control in a jurisdiction with a materially lower tax rate, where there is no reasonable business need for the retention. It is China's individual CFC rule in all but name and it is aimed squarely at a Chinese resident holding a Panamanian, BVI or Hong Kong company.
Loss of nationality. A Chinese national who acquires a foreign nationality of their own accord automatically loses Chinese nationality, but the loss is only given effect when the person surrenders the hukou and passport. Families who quietly hold two passports are living in a legal gap that surfaces at the border, at inheritance, and when a Chinese bank or court asks which identity applies.
Exit bans. Chinese law allows an exit ban on a person involved in unresolved civil litigation, a debt or a criminal investigation, and on family members of those under investigation. They are used in commercial disputes and are not announced until the person is at the airport. For a business owner with any unresolved dispute, the practical rule is to settle it before relocating, not after.
The Structural Layer
FTR's default, a Panamanian Private Interest Foundation holding a Panamanian SA with a modest director's salary paid where the client lives, plainly does not fit a Chinese tax resident. Article 8 attributes the SA's retained profits back to the individual, the foundation is opaque to nobody who matters because CRS reports the controlling person to the STA, the funding cannot cross the border under the quota, and there is no China-Panama treaty to soften any of it. Building the structure first and dealing with residency later is the most common error in this market and it is the one FTR refuses to make.
The sequence that works has four steps, in order. First, establish what wealth is already lawfully outside China: earnings from years abroad, Hong Kong listed holdings, dividends from a Circular 37-registered offshore company, proceeds of overseas property, or a legitimate overseas direct investment approval for a business. FTR structures only funds with a documented lawful exit; that is a policy position, not a preference. Second, break Chinese tax residency in substance, which means relocating the family, the habitual home and the economic centre, and ideally regularising nationality. Third, establish the new tax residency and satisfy its own rules, which for Singapore, Australia, Canada or the UAE are covered in their profiles. Fourth, and only then, build the holding layer.
Once the client is a tax resident of Singapore, the UAE or a Latin American country, the Panamanian default works normally: foundation for succession across a family that now spans two or three jurisdictions, SA for the operating or holding activity, salary and dividends flowing to the new residence. A family with education-driven residency in Australia or Canada meets those countries' CFC and attribution rules and needs the adaptations described in their profiles. A family choosing the United States must be advised that a US person is taxed on worldwide income and that a Panamanian foundation is, for US purposes, usually a foreign trust with its own reporting; the non-CRS advantage does not survive becoming a US tax resident.
Where V2's point about United States structures applies is narrower: a non-US-resident family using a US LLC or a US-situs trust with a professional trustee as a holding vehicle, because the United States does not exchange under CRS. That can be a defensible diversification of jurisdictional exposure. It is not a secrecy device, since the family remains reportable wherever its members are actually tax resident, and FTR presents it as the former, never the latter.
Info-Sharing Reality (CRS and FATCA)
China joined CRS with first exchanges in September 2018 and is a full participant. Every financial account held by a Chinese tax resident in a participating jurisdiction is reported annually to the State Taxation Administration: balance, interest, dividends and gross proceeds, with the controlling persons of any passive company, foundation or trust identified. Singapore, Hong Kong, Switzerland, the UAE, the Cayman Islands, the BVI, Panama and every EU state exchange with China. A Chinese HNW client whose objective is that Beijing should not see the overseas balance sheet is not achieved by choosing any of those places for the money; it is achieved only by ceasing to be a Chinese tax resident in substance, after which the reports go to the new residence country instead.
The United States is the exception. It is not a CRS participant and does not report to China. Chinese banks, for their part, have not implemented FATCA reporting, because the China-US intergovernmental agreement was agreed in substance in June 2014 and has never been signed. A US person with accounts in China is still obliged to report them, and the absence of an IGA does not change that.
Chinese resident individuals also carry their own reporting duty on overseas income, and since 2025 the STA has demonstrated that it matches CRS data against returns. The privacy that many families assumed they had in Singapore or Switzerland ended in 2018; the enforcement gap that let them behave as though it had not ended is now closing.
Banking Reality
Inside China the system is dominated by the state banks: ICBC, Bank of China, China Construction Bank, Agricultural Bank of China and Bank of Communications, with China Merchants Bank the strongest private banking franchise. Private banking starts at CNY 6 million to 10 million of financial assets. Foreign residents can open accounts with a passport, residence permit and local phone number, and daily life then runs through WeChat Pay and Alipay, which since 2023 accept foreign cards more readily. Every one of these banks is subject to Chinese regulatory oversight and reports to it, and their overseas branches follow the same instruction from head office. A Bank of China account in Hong Kong or Singapore is not an offshore account in any sense that matters.
Outside China the reality for a Chinese passport holder is enhanced due diligence everywhere. Singapore's banks tightened sharply after the 2023 money-laundering case involving Chinese-born clients with multiple passports, and now expect a documented trail from the original source of wealth through the lawful exit from China to the deposit. Swiss and Hong Kong private banks apply similar standards. A second passport from a Caribbean or Pacific citizenship-by-investment programme, held alongside a Chinese one, is a red flag rather than a solution. Realistic onboarding at a Singapore or Swiss private bank for a Chinese client is two to four months with full documentation, and refusal without reasons is common. Panamanian banks have become more willing to take Chinese clients over time, again with full source-of-funds evidence, and remain slower than Asian alternatives.
Moving wealth out is constrained by the USD 50,000 quota, by the monitoring of informal channels and by periodic enforcement campaigns. Golden Visa and citizenship-by-investment programmes have been used as one legitimate outbound route, because the investment itself can sometimes obtain remittance approval; that approval is discretionary and has become harder to obtain.
Cost of Doing Business
A wholly foreign-owned enterprise costs USD 5,000 to 15,000 to establish through an agent, with no minimum paid-in capital but a registered capital commitment that must be realistic, and USD 5,000 to 15,000 a year in accounting, monthly and quarterly tax filings, annual audit and the annual inspection. Timelines run one to three months and the entity cannot open a bank account or hire until the licence issues. Against the set, a Panamanian SA runs USD 1,500 to 2,500 to establish and USD 1,000 to 1,800 a year, Singapore about three times the Panamanian setup at USD 4,500 to 7,500 with USD 4,000 to 8,000 in annual compliance, and Hong Kong slightly below Singapore. A Chinese WFOE is therefore in Singapore's cost bracket with far heavier compliance, and it exists to trade in China, not to hold anything. No FTR client should form one for structuring reasons.
Cost of Living
For a client posted to a first-tier city rather than leaving one, three tiers apply. Lean: a single professional in a one-bedroom flat outside the centre of Shanghai or Shenzhen lives on USD 1,800 to 2,500 a month. Comfortable: a couple in a good central two-bedroom, private health insurance and regular travel, USD 3,000 to 5,000, with central Shanghai rents of USD 1,500 to 3,000. HNW family: a house in a compound, a driver and two children at an international school at USD 30,000 to 45,000 a year each, USD 12,000 to 20,000 a month. Public healthcare is competent and cheap but crowded and Chinese-speaking; international hospitals in Shanghai and Beijing are excellent and expensive, so comprehensive international insurance at USD 3,000 to 8,000 a year per adult is standard. Transport is cheap and superb. Children of Chinese nationals are generally barred from international schools, which matters for returning families with mixed passports.
Cultural and Practical Considerations
Language and daily systems. Mandarin is the floor for everything outside the international bubbles of Shanghai and Beijing: banks, tax bureaus, hospitals, landlords and the police. Daily life runs through a Chinese phone number, a Chinese bank card and the WeChat and Alipay super-apps, all real-name registered, and a foreigner outside that system cannot pay for a taxi. The Great Firewall blocks Google, most Western social media and many news sites; VPNs are widely used and technically unlawful, and their reliability is deliberately variable.
Women. Women are legally equal, own property, direct companies and travel freely; street safety for women is among the best of any large country, and violent crime against foreigners is rare. The exposures are in family law and workplace culture: custody disputes involving a Chinese parent are decided in Chinese courts, which favour the Chinese parent and the hukou location, and foreign custody orders are not enforced. Business culture is hierarchical and drinking-heavy, and a woman negotiating alone is often assumed to be a subordinate.
LGBT residents. Same-sex activity has been legal since 1997 and there is no recognition of same-sex relationships, no protection from discrimination and no dependant visa for a same-sex partner. Enforcement is not the risk; censorship and the shrinking of visible community are. Discreet foreign couples live without incident in the big cities.
Political and personal security. This is the section that matters. The state is present in every transaction and has, since the 2023 expansion of the counter-espionage law, a broad view of what constitutes state secrets; foreign consultancy and due diligence firms have been raided. Several Western governments' travel advisories warn of arbitrary detention and exit bans for their citizens, including those of Chinese descent. Anyone with unresolved commercial disputes, outstanding debts or a professional interest in politically sensitive subjects carries real risk. Policy shifts overnight and without appeal, as the tutoring, gaming and property sectors learned in 2021, and a foreign resident has no political recourse at all.
Order, noise and pace. Cities are dense, loud and relentlessly efficient; infrastructure works on time, and so must you. Someone who needs quiet, slowness or informality will not find them. Air quality has improved markedly but Beijing winters are still hard on respiratory and cardiac conditions; summers in the south are hot and humid.
Integration, religion and schooling. Social integration beyond colleagues and expatriate circles is difficult without fluent Mandarin and family ties, and the expat community in Shanghai is large enough to substitute for years. Religious practice is tolerated for foreigners at registered venues and monitored; proselytising is illegal. Halal food is widely available, kosher is not. International schools are excellent and expensive, and the barrier on Chinese nationals' children has broken up many returning families' plans.
For Chinese-origin clients abroad. The relevant cultural facts run the other way: ageing parents who cannot or will not leave, the hukou that anchors domicile, the expectation that the family business continues, and the exposure of any relative who remains to pressure over the family's overseas affairs. Plans that ignore the parents rarely execute.
For Retirees
China is not a retirement destination for foreigners, and Chinese retirees leaving face the domicile test above plus the quota; the Pensionado-type routes in Panama, Malaysia and Thailand are where they land.
For Digital Nomads and Remote Professionals
Unworkable; no visa, no payment rails without residence, no reliable internet to the outside world.
For Online Business Owners and Entrepreneurs
A Chinese-resident owner of an offshore online business is caught by Article 8 and Circular 37; the answer is the residency exit in The Structural Layer, then the Panama or Singapore company.
For Multinational Business Owners
Onshore operations sit in a WFOE at 25%; the offshore holding should already be Circular 37-registered, and any restructuring starts with confirming that it is.
For High Net Worth (HNW) Families and Investors
This is the profile's core reader. Genuine residency change first, then the holding layer; the United States for non-CRS positioning and education, the UAE for tax plus distance, Australia, Canada and the EU for family life, Singapore for banking, Panama as the USD structural layer. Beijing's visibility ends when Chinese tax residency ends, not before, and FTR's counsel is frank about that.
Common Traps
Any plan that starts with an offshore structure and defers the residency question. Any plan that needs more than USD 50,000 a year to leave China without a documented approval, and FTR will not assist with the informal alternatives. Holding a foreign residence card while keeping hukou, home and business in China and expecting a different tax or CRS outcome. Buying a second passport to present to a Singapore bank. Assuming Hong Kong is politically or legally separate for planning purposes: it is a separate tax jurisdiction and a CRS partner of the mainland, and that is all. Relocating with an unresolved lawsuit or debt behind you. And, for the foreigner considering a posting: anyone whose work touches politics, data or due diligence, anyone who cannot accept surveillance as a background condition, and any family whose children hold Chinese passports and expect international schooling.
Next Steps
Chinese-connected cross-border planning is a sequenced exercise, and the sequence is lawful capital position, residency exit, new residency, then structure. FTR works with specialist China counsel on the first two steps and builds the last two. Book a scoping call.
Important note: General information. Not personal tax, legal, or financial advice. Speak to a qualified adviser at FTR or elsewhere before acting.
Continue reading
Suggested next, chosen by our partners.


